Educational overview only. Prudent Guardian (inspirecodingedu.com) is not an insurance company, broker, law firm, or registered investment adviser, and does not provide personalized insurance, investment, tax, medical, or legal advice. Verify details with licensed professionals and official issuers.
Market-value adjustment (MVA) entries appear as specific line items on formal early withdrawal confirmation documents for fixed-rate financial products like annuities and certificates of deposit. These adjustments are applied when you withdraw funds before the end of a stated guarantee period, and their value fluctuates based on current interest rates relative to the rate locked when you opened the product. Failing to locate and verify MVA line items on your confirmation can lead to unexpected gaps between your expected disbursement and the actual funds you receive, so cross-referencing every listed charge is a critical step before you sign off on the withdrawal request. Prudent Guardian creates this educational paperwork guidance to help you cross-check official documents against your own records, with no binding legal or financial advice contained herein.
Withdrawal confirmation form sections listing official MVA calculations
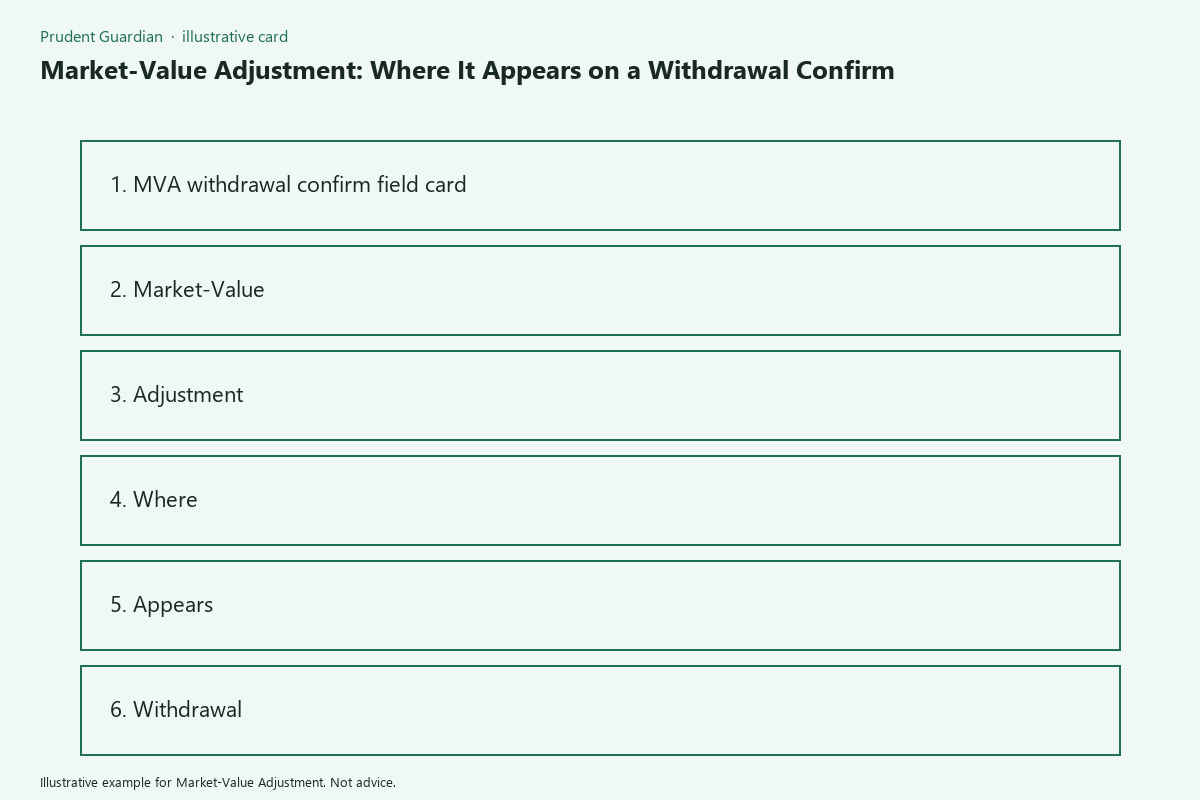
Digital and printed withdrawal confirmation forms follow a standardized structure for regulated fixed-rate products, with MVA calculations placed in a dedicated subsection separate from standard penalties, fees, and tax withholdings. Most issuers position this section directly below the early withdrawal penalty line in the “Adjustments to Account Value” portion of the form, so you do not have to sift through fine print to locate it. To make verification easier, use the following MVA withdrawal-confirm field card to cross-check every entry against your contract terms and account records:
| Field Label | Typical Form Section Location | Required Verification Step | Illustrative Example Value |
|---|---|---|---|
| Gross Pre-Withdrawal Account Value | Account Summary header (top 1/3 of form) | Match to your most recent official account statement minus any pending, unprocessed withdrawals or credits | Illustrative example: $125,000 |
| Early Withdrawal Penalty (Non-MVA) | Penalty Disclosures subsection | Confirm the percentage used aligns with the penalty schedule stated in your original product contract | Illustrative example: $6,250 (5% of withdrawn principal for 12 months remaining on guarantee period) |
| Applicable Market Value Adjustment | MVA Calculation subsection (directly below non-MVA penalty line) | Confirm the adjustment sign matches current rate trends (negative if current rates are higher than your locked rate, positive if lower) and aligns with contract MVA terms | Illustrative example: -$2,100 (rate adjustment for 18 months remaining on a 3.5% fixed annuity when current comparable rates are 4.7%) |
| Net Disbursement Before Tax Withholdings | Disbursement Summary subsection | Calculate manually using the formula: (Gross withdrawn principal) minus (non-MVA penalty) minus (negative MVA) or plus (positive MVA) to confirm no arithmetic errors | Illustrative example: $116,650 for a full account withdrawal |
| Final Disbursement Amount | Bottom of Disbursement Summary | Confirm matches your manual calculation minus any applicable federal, state, or local tax withholdings you elected | Illustrative example: $99,152.50 after 15% federal tax withholding |
If any field on your confirmation does not match the expected value per your verification step, reach out to the issuer’s customer service team immediately to request a revised calculation before signing the form. Never sign a withdrawal confirmation with an unlabeled adjustment that you cannot confirm is the stated MVA from your contract.
Mailed withdrawal letter line items noting applied MVA deduction values
Mailed physical withdrawal confirmations often include more granular line items than digital portal versions, as they are considered official legal records of the withdrawal transaction. For mailed letters, the MVA will be listed as a standalone line item in the “Adjustments to Disbursement” section, which is separate from tax withholdings, administrative processing fees, and contractual early withdrawal penalties. If your MVA is a deduction (applied when current interest rates are higher than the rate you locked in at account opening), it will be listed with a minus sign or labeled as “Deduction: MVA”. If it is a credit (applied when current rates are lower than your locked rate), it will be listed with a plus sign or labeled as “Credit: MVA”. Many issuers use abbreviations for space, so look for terms like “MVA Adj”, “Market Val Adj”, or “Market Adjustment” if the full term is not spelled out. For partial early withdrawals, confirm that the MVA is only applied to the amount you are withdrawing, not your full remaining account balance, as this is a common calculation error you can catch quickly by cross-referencing the withdrawn principal line item with the MVA base value listed in the calculation notes.
Adjustment disclosure box text explaining MVA calculation assumptions
All regulated fixed-rate product issuers are required to include a standardized disclosure box on withdrawal confirmations that lists every assumption used to calculate your MVA, so you can replicate the math on your own to confirm accuracy. This box is usually positioned directly below the MVA line item, and will include the following details: the remaining number of months left on your original guarantee period, the current benchmark interest rate the issuer uses for comparable new products of the same term length, the original annual percentage rate you locked in when you opened the account, and any applicable MVA floors or ceilings stated in your original contract that limit how high or low the adjustment can be. Some issuers also include the full calculation formula in this box, for example: MVA = (Withdrawn Principal) x (Current Rate – Locked Rate) x (Remaining Term / 12). If any assumption listed in this box does not match your contract terms (for example, the remaining term is listed as 36 months when you know your guarantee period ends in 18 months), you can submit a formal correction request to the issuer within the stated dispute window, which is usually 10 to 15 business days from the date printed on the confirmation.
Filed record folder storage location for signed MVA withdrawal confirmations
Proper storage of your signed MVA withdrawal confirmation is critical for tax filing, audit defense, and future disputes with the issuer. You should keep both physical and digital copies of all MVA-adjusted withdrawal confirmations for the full life of the account, plus a minimum of 7 years after the account is closed, to comply with federal tax record keeping requirements. Physical copies should be stored in a fireproof, locked file cabinet in the same folder as your original product contract, annual account statements, and any written correspondence related to the withdrawal request. Label the folder tab clearly with the product type, issuer name, and withdrawal date to speed up retrieval if you need to access the records later. Digital copies should be stored in an encrypted cloud folder or password-protected external hard drive, with a file name that follows a consistent naming convention, for example “2024-03-15_5-Year-Fixed-Annuity_XYZ-Insurance_MVA-Withdrawal-Confirm.pdf”. If you work with a licensed tax professional or financial advisor, you can share a copy of the confirmation for their records, but always keep a primary copy in your personal storage location to avoid gaps if your professional changes firms or loses access to your files. If you submit a correction request for an MVA calculation, store a copy of the request, any supporting documentation, and the revised confirmation in the same folder as the original document.
Official processing schedule timelines for MVA-adjusted fund disbursements
MVA-adjusted early withdrawals typically take longer to process than standard on-maturity withdrawals, because the issuer must verify the MVA calculation against current market rates and confirm all contract terms are met before releasing funds. Illustrative example: most issuers process MVA-adjusted disbursements within 7 to 10 business days from the date you sign and return the withdrawal confirmation, compared to 2 to 3 business days for withdrawals requested after the guarantee period ends. If you elected direct deposit for your disbursement, the funds will usually post to your linked bank account 1 to 2 business days after processing is complete. If you elected a mailed paper check, you can expect delivery via USPS First Class Mail within an additional 3 to 5 business days after processing. If you do not receive your disbursement within 15 business days of signing the confirmation, contact the issuer’s customer service team immediately to request a status update, as delays can indicate an error in the MVA calculation, missing paperwork, or a hold placed on the account for identity verification. If you dispute the MVA amount listed on your confirmation, the issuer may place a temporary hold on the disbursement until the dispute is resolved, so submit any correction requests as soon as you receive the confirmation to avoid unnecessary delays to your funds.
Pull your active fixed annuity or CD contract to note the stated MVA calculation terms, so you can cross-reference them immediately when you receive a withdrawal confirmation for any future early withdrawal request.
Written by the Prudent Guardian editors.